

When experiencing a separation in Brampton, a common concern is, ‘How do I safeguard my property during a divorce?’ The solution involves taking prompt and careful measures in accordance with Ontario’s *Family Law Act*. It’s important to avoid concealing assets or engaging in deceptive practices. Instead, begin by creating a comprehensive inventory of all family assets and liabilities. Additionally, systematically gather all essential financial documents. This approach not only ensures proper preparation but also lays the foundation for an equitable division of property. Consulting with Badesha Law, a knowledgeable family lawyer in Brampton, can provide valuable guidance and support through this process.
Your First Financial Moves When Separation Looms – Guidance from a Brampton Family Lawyer
Staring down a separation in Brampton is overwhelming, and it’s completely normal to feel anxious about your financial security. The entire process of dividing property is guided by Ontario’s legal framework, which is built on fairness and full financial disclosure.
Protecting your assets isn’t about deception. In fact, trying to hide money or property can lead to severe legal penalties under both family law and, in extreme cases, the Criminal Code of Canada. True protection comes from creating a clear, honest, and complete picture of your financial life as a couple. This initial stage is your chance to gain clarity and take back some control.
Start with a Detailed Financial Inventory
Before you can even begin talking about who gets what, you need to know exactly what’s on the table. This means creating a detailed inventory of everything you and your spouse own and owe as of your date of separation. Think of it as a complete financial snapshot of your married life.
Your inventory list needs to be exhaustive. Leave nothing out. It should include:
- Real Estate: The matrimonial home in Brampton, any rental properties, the family cottage, or other real estate.
- Bank Accounts: All chequing, savings, and joint accounts.
- Investments: Stocks, bonds, mutual funds, GICs, and RRSPs.
- Vehicles: Cars, trucks, motorcycles, boats, and any other recreational vehicles.
- Pensions and Retirement Plans: Both private employer plans and government pensions.
- Personal Property: Valuables like jewellery, art collections, and high-end electronics.
- Business Interests: Any shares or ownership you have in a business.
- Debts and Liabilities: Mortgages, car loans, lines of credit, and credit card balances.
This step is non-negotiable. A thorough inventory prevents nasty surprises down the road and makes sure every asset is accounted for during the equalization process.
Gather Your Essential Documents
Once you have your list, it’s time to find the paperwork that proves the existence and value of each item. This documentation is the evidence you’ll rely on. It’s incredibly important to make copies of everything and keep them in a secure location your spouse can’t access, like with a trusted friend, family member, or in a new safety deposit box.
Taking proactive steps to organize your financial records isn’t just good practice; it’s a strategic move. A well-documented financial file empowers you and your lawyer to build a strong case, ensuring transparency and preventing assets from being overlooked or undervalued during negotiations.
Key documents you need to find and copy include:
- Tax Returns and Notices of Assessment: At least the last three years for both you and your spouse.
- Bank and Investment Statements: Statements for all accounts covering the period from the date of marriage to the date of separation.
- Property Deeds and Mortgage Statements: For any real estate you own.
- Pension and RRSP Statements: The most recent statements available are a good start.
- Vehicle Ownership Documents: Proof of ownership and any information on outstanding loans.
- Credit Card and Loan Statements: To accurately list all shared debts.
Gathering these documents lays the foundation for your financial disclosure, which is a mandatory step in any Ontario divorce. It ensures you’re prepared for what comes next and helps protect your property by establishing a clear, provable financial history from the get-go.
Immediate Asset Protection Checklist
To get started, it helps to have a clear, actionable checklist. The table below summarizes the critical first steps you should take to preserve your financial standing right at the outset of your separation in Brampton.
| Action Item | Why It’s Critical in Brampton | Documents to Gather |
|---|---|---|
| Inventory All Assets | Ontario’s Family Law Act requires a full accounting of all property for equalization. Missing an asset can cost you later. | List of all real estate, bank accounts, investments, pensions, vehicles, and valuable personal items. |
| List All Debts | Both assets and debts are shared. You need a clear picture of mortgages, loans, and credit card balances to calculate Net Family Property. | Recent mortgage statements, car loan agreements, line of credit statements, and credit card bills. |
| Gather Financial Statements | These documents provide proof of value at key dates (date of marriage and date of separation), which is essential for the equalization calculation. | Bank, investment, and RRSP statements from the date of marriage and the date of separation. |
| Copy Tax Returns | Your T1 Generals and Notices of Assessment from the CRA for the last 3 years are mandatory for financial disclosure in court. | Both spouses’ income tax returns and Notices of Assessment (at least the last 3 years). |
| Secure Important Papers | Having your own copies prevents documents from “disappearing” and ensures you and your lawyer have the information you need. | Property deeds, vehicle ownerships, insurance policies, and business records. Make digital and physical copies. |
This checklist isn’t exhaustive, but it covers the non-negotiable first moves. Acting quickly to get this information organized will put you in a much stronger position as you move forward.
Decoding the Matrimonial Home and Equalization
When you’re trying to figure out how to protect your property during a divorce, two concepts from Ontario’s Family Law Act are absolutely critical: the Matrimonial Home and Equalization. Getting a handle on these isn’t just helpful—it’s the foundation for setting realistic expectations for your financial future in Brampton. They explain why your family home gets special treatment and how all the wealth you built together gets divided.
What Makes the Matrimonial Home So Special?
In Ontario, the home you and your spouse ordinarily lived in during your marriage is considered the matrimonial home. This gives it a unique status under the law, and it doesn’t matter whose name is on the title.
This means even if you owned your Brampton house before you got married and it’s solely in your name, it becomes the matrimonial home once you live in it as a family. From that point on, your spouse has an equal right to live there. Neither of you can sell it, take out a mortgage on it, or kick the other person out without their consent or a court order. It’s a powerful protection designed to ensure stability during a very unstable time.
The process always starts with a clear-eyed inventory of what you have, followed by gathering all the necessary proof, and only then can you build a smart strategy.
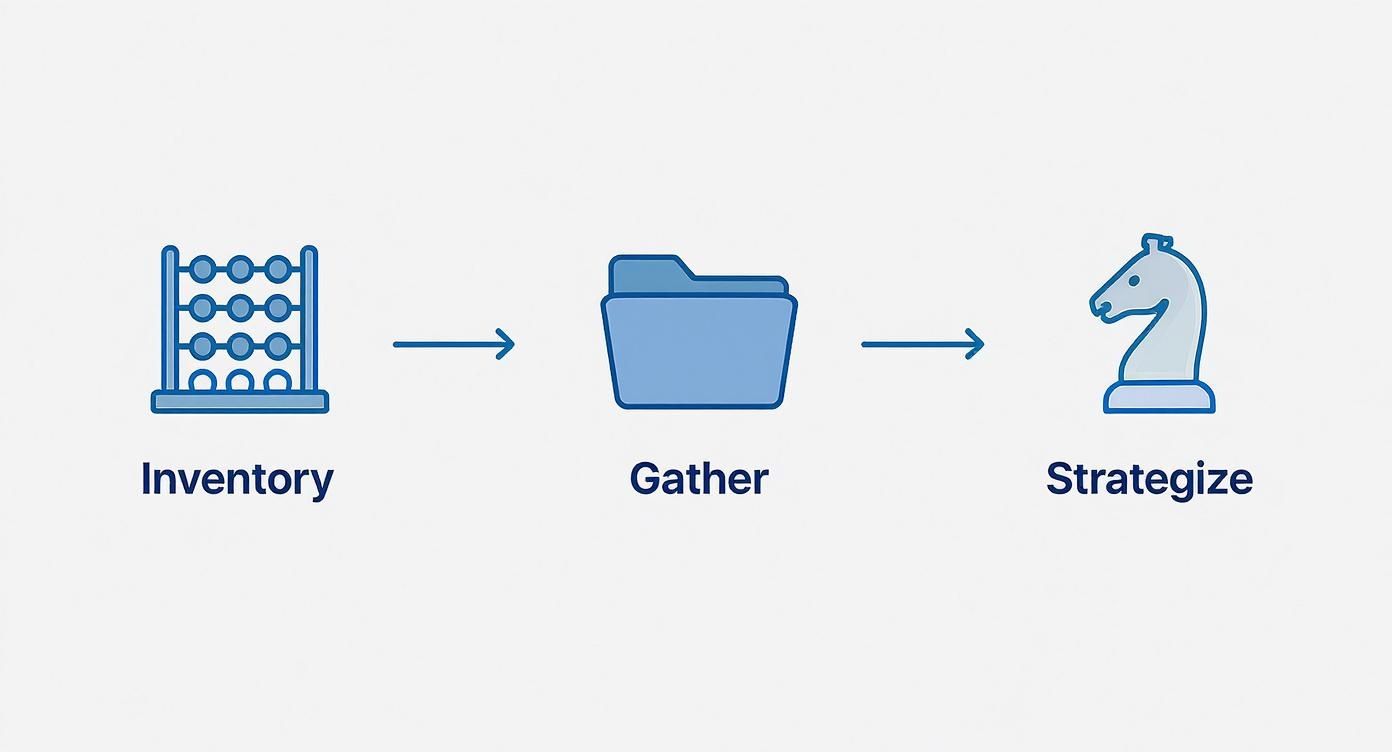
This flow highlights a key takeaway for our Brampton clients: protecting your assets isn’t about hiding things. It’s about meticulous organization and having a complete, honest financial picture from the very beginning.
Understanding Equalization of Net Family Property
Beyond the home, Ontario law is built on the idea that both spouses should share equally in the wealth built up during the marriage. This process is called equalization.
Think of it as a formula, not a feeling. The goal is to calculate the growth in each person’s net worth from the wedding day to the separation day, and then “equalize” the difference.
Here’s the basic idea:
- Calculate Net Family Property (NFP) for each spouse.
- Find the difference between the higher and lower NFP.
- The spouse with the higher NFP pays half of that difference to the other spouse.
This payment ensures both partners leave the marriage with an equal share of the value created during their time together.
How Net Family Property Is Calculated
Calculating your NFP is essentially a detailed accounting of your financial life. We take a snapshot at two specific moments: the day you married and the day you separated.
The basic formula looks like this:
- Value of your assets on the date of separation
- Minus your debts on the date of separation
- Minus the value of your assets on the date of marriage
- Minus your debts on the date of marriage
- Equals your Net Family Property
Certain assets can sometimes be excluded, like gifts or inheritances you received during the marriage, but only if you kept them totally separate and didn’t use them for the family. The matrimonial home is the big exception here—its value is almost always included in the calculation, even if you owned it long before the wedding.
The concept of equalization is the bedrock of Ontario family law. It recognizes marriage as an economic partnership. Any attempt to quickly sell assets or move money after separation is usually pointless, as courts will almost always use the ‘date of separation’ value for their calculations. Full transparency isn’t just a good idea; it’s required.
While Ontario uses this equalization model, other places have different rules. For instance, a critical strategy for protecting property in a California divorce is the careful tracing and documentation of “separate property.” California law makes a hard distinction between community property (acquired during marriage) and separate property (owned before marriage or received as a gift or inheritance). If you can prove an asset is separate, it won’t be divided. This shows why, no matter where you are, meticulous record-keeping is universally important.
A Brampton Scenario
Let’s make this real. Imagine a Brampton couple, Priya and Raj, are separating.
- After all the calculations, Priya’s NFP is $400,000.
- Raj’s NFP comes out to $100,000.
The total family wealth they accumulated during the marriage is $500,000. To equalize this, they should each walk away with $250,000.
To get there, Priya, who has the higher NFP, needs to make an equalization payment to Raj. We find the difference between their NFPs ($300,000) and divide it by two.
Priya owes Raj an equalization payment of $150,000. This payment doesn’t have to be a cheque; it can be made by transferring assets, like a portion of an RRSP, or from the cash generated by selling the matrimonial home.
Navigating Complex Assets Like Businesses and Pensions
When you’re trying to figure out how to protect your property in a divorce, the financial picture often extends far beyond the family home. Things get complicated fast when you have joint bank accounts, a family business, or retirement funds in the mix. These assets are usually tied directly to your long-term security, making their fair division one of the most critical parts of the process.
Let’s start with joint bank accounts. The first instinct for many is fear—what if my spouse drains the account and leaves me with nothing? It’s a valid concern, but emptying a joint account yourself can be seen as acting in bad faith and can really hurt you down the line.
A much better approach is to try and agree with your spouse to freeze the account. Another option is to divide the funds equally and move them into separate, individual accounts. This ensures you both have money for immediate expenses while preserving the rest for the final equalization calculation. Acting on your own without communication almost always complicates things, so talking it through—ideally via your lawyers—is key.
Valuing a Brampton Business in Divorce
For many entrepreneurs in Brampton, their business is their single most significant asset. Under Ontario’s Family Law Act, any business that was started or grew in value during the marriage is considered property to be divided. It makes no difference if your spouse was never involved in the day-to-day operations; the value accumulated is seen as a product of the marital partnership.
Protecting your business starts with getting a proper valuation. This isn’t a simple DIY task. It almost always requires a Chartered Business Valuator (CBV) to determine the business’s fair market value as of your separation date. The valuator will look at everything:
- Tangible assets like equipment, real estate, and inventory.
- Intangible assets such as goodwill, client lists, and brand reputation.
- Liabilities and any outstanding business debts.
The final value they land on gets included in your Net Family Property calculation for equalization. It’s a common mistake to think you can shield your business by putting it in someone else’s name or deliberately undervaluing it. These moves are easy for forensic accountants to spot and can lead to serious legal penalties.
Demystifying the Division of Pensions and Retirement Funds
Pensions, RRSPs, and other retirement funds are often one of a couple’s most valuable assets—sometimes worth even more than the matrimonial home. These are treated as family property and are subject to equalization. The portion of the pension’s value that was earned during the marriage is what needs to be accounted for.
Figuring out the value of a pension for division can be incredibly complex, especially for defined benefit plans common in government and public sector jobs. You’ll almost certainly need a professional actuary to calculate the correct “commuted value” for the period of the marriage.
Pensions represent deferred income earned during the marriage. Failing to have them professionally valued is one of the most significant and costly mistakes people make in a divorce. The future income stream they represent must be fairly divided to protect both spouses’ long-term financial health.
While Ontario’s laws dictate how these assets are treated, legal frameworks can vary significantly by jurisdiction. For example, protecting your property in a divorce in California is heavily shaped by community property laws, which typically mandate a 50/50 split of assets acquired during the marriage. This rigid rule underscores the universal importance of accurate valuation and full disclosure, no matter the local laws. You can explore more about these distinct legal systems and their impact on divorce statistics.
Once the pension is properly valued, the amount can be equalized in a couple of ways:
- Immediate Transfer: A portion of the pension can be transferred directly from one spouse’s plan to the other’s locked-in retirement account. This is a clean way to handle it.
- Asset Trade-off: The spouse with the pension can keep it all but “buy out” the other’s share by giving them another asset of equal value, like a larger portion of the home’s equity.
Navigating these complex financial instruments is not something to do alone. You need professional guidance to ensure the valuation is accurate and the division is fair, securing your retirement future.
Using Legal Tools to Prevent Your Ex from Hiding Assets
One of the biggest fears people in Brampton have during a separation is that their spouse will start secretly selling, transferring, or draining marital property before it can be divided fairly. It’s a valid concern. Actions like these can seriously damage your financial future.
Thankfully, Ontario’s legal system has powerful tools to stop this from happening. If you have good reason to believe your spouse is about to make a major move with family assets, you can’t afford to just wait and see. The law offers ways to freeze property right in its tracks, preserving everything until a final settlement or court order is reached.
What is a Preservation Order?
In Ontario, the main tool we use to stop a spouse from getting rid of assets is a preservation order, which you’ll often hear called an injunction. It’s a court order that effectively freezes specific property, making it illegal for either spouse to sell, mortgage, or dispose of it without the other’s permission or a judge’s approval.
This isn’t a step the court takes lightly. A Brampton judge will only grant a preservation order if you can show there’s a real, genuine risk that your spouse is about to dissipate assets. Vague suspicions won’t cut it—you need to bring evidence.
When Will a Brampton Court Grant an Injunction?
To get a preservation order, your lawyer needs to build a compelling case. Courts are most likely to step in when there’s a clear attempt to undermine the equalization process.
Here are a few real-world scenarios where an injunction might be granted:
- Shady Business Deals: Your spouse owns a business and suddenly tries to sell their shares to a family member for way less than they’re worth.
- Moving Money Offshore: You find wire transfer receipts showing your spouse is sending large sums of money to an overseas bank account.
- Surprise Property Listings: You discover your spouse has listed a rental property you both own for sale without ever telling you.
- Cashing Out Investments: Your spouse suddenly starts liquidating shared investments or RRSPs, which is completely out of character for their usual financial behaviour.
In situations like these, a preservation order is a critical tool to keep the financial situation stable and ensure every asset is on the table for a fair division.
A preservation order sends a clear message: all assets must stay put until they are properly dealt with under the Family Law Act. It’s a crucial legal safeguard that stops one person from unfairly changing the financial picture before negotiations even start.
The Criminal Code and Fraudulent Asset Hiding
This goes beyond just family law. Intentionally hiding or fraudulently getting rid of assets to cheat your spouse out of their rightful claim can have very severe consequences. Section 392 of the Criminal Code of Canada makes it a crime to dispose of or hide property with the intent to defraud creditors—and a spouse with a claim to that property can fall into that category.
Now, meeting this high standard is tough, and criminal charges are rare in divorce cases. But it shows just how seriously the legal system treats this kind of fraudulent behaviour. While the main goal in family court is a fair property division, knowing these criminal provisions exist adds another layer of protection and acts as a strong deterrent against deceit.
While legal orders are a powerful tool, some couples opt for proactive agreements to define asset division from the outset. For instance, in other jurisdictions, prenuptial and postnuptial agreements are widely used to specify how property will be handled in a divorce, bypassing default legal rules. Recent trends show a significant increase in couples using these contracts to protect individual assets. You can discover more insights about the rising popularity of prenuptial agreements and related divorce statistics.
The Best Defence: How the Best Family Lawyer in Brampton Helps You Craft a Strong Separation Agreement
While court orders and injunctions are powerful tools, they usually mean you’re on an adversarial path. The most effective, efficient, and empowering way to protect your property during a divorce is by creating a comprehensive Separation Agreement with your spouse. This legally binding contract is your single most important tool for gaining certainty and control over your future.
Think of a Separation Agreement as a detailed roadmap for your financial split. Instead of a judge in a Brampton courthouse making decisions about your life, you and your spouse sit down—with your respective lawyers guiding you—and make those decisions yourselves. The amount of time, money, and emotional stress this saves compared to a court battle is immense.
Taking Control of Your Financial Future
A well-drafted agreement can cover every single aspect of your separation. It’s your chance to be creative and find solutions that work for your unique family situation, rather than being forced into a one-size-fits-all outcome from a judge.
The scope of a Separation Agreement is incredibly broad and can spell out exactly how to handle things like:
- The Matrimonial Home: Who gets it? Will one spouse buy the other out, or will it be sold with the proceeds divided down the middle?
- The Equalization Payment: The agreement will state the exact equalization amount and the payment terms—whether it’s a lump sum, an asset transfer (like an RRSP rollover), or structured payments over time.
- Specific Assets: You can decide who keeps the car, the cottage furniture, or even specific sentimental items that a court wouldn’t care about.
- Debts and Liabilities: It clearly outlines who is responsible for paying off the mortgage, credit card balances, or lines of credit, protecting you from creditors coming after you for your ex’s debts.
When you settle these matters in an agreement, you eliminate the unknown. You know exactly what you owe and what you’re entitled to, which allows you to move forward with a clear, stable plan.
The Non-Negotiable Step: Independent Legal Advice
Here’s a crucial point for anyone in Brampton. Under Ontario’s Family Law Act, for a Separation Agreement to be legally binding and hold up in court, both parties must provide full and honest financial disclosure. Even more importantly, each spouse must obtain Independent Legal Advice (ILA) from their own lawyer before signing it.
This isn’t just a friendly suggestion; it’s a critical legal requirement. ILA ensures that:
- You completely understand the terms of the agreement and its long-term consequences.
- You know your rights and obligations under Ontario law.
- You are not being pressured or forced into signing something that isn’t fair.
A family lawyer will review the entire document with you, flag any potential red flags, and confirm that it truly protects your interests. If you skip this step, a court could easily set aside the agreement down the road, undoing everything you worked to achieve and throwing your financial life back into chaos.
A Separation Agreement without Independent Legal Advice is not worth the paper it’s written on. It’s the final, essential step that transforms a simple document into a powerful, legally enforceable tool that protects your property and secures your future.
Why an Agreement Is Almost Always Better Than Court
Going to court should be a last resort. It’s a public process, it’s incredibly expensive, and at the end of the day, the final decision is completely out of your hands. Crafting a Separation Agreement keeps your affairs private and encourages collaboration.
It empowers you and your spouse to end your marriage with dignity and respect, which is especially important when children are involved. By proactively defining the terms of your separation, you are taking the most powerful step possible to protect your property and build a secure foundation for your new beginning.
Common Questions on Protecting Your Assets During a Divorce
When you’re facing a separation in Brampton, a flood of questions about your home, your savings, and your future can feel overwhelming. With emotions running high, you need clear, practical answers grounded in Ontario’s Family Law Act. We’ll tackle some of the most common concerns we hear every day, giving you the straightforward information you need to protect what’s yours.
Can My Spouse Kick Me Out of Our Brampton Home?
This is usually the first and most urgent fear people have. The short answer is a firm no.
In Ontario, if the property was your regular family residence, it’s legally considered the “matrimonial home.” This status gives you special protections, and it doesn’t matter whose name is on the title.
Both of you have an equal right to live in the matrimonial home until there’s a court order or a signed Separation Agreement that states otherwise. Your spouse can’t legally change the locks on you, sell the house from under you, or take out a new mortgage without your explicit written consent. These rules are in place to ensure stability for you and any children while you navigate the separation.
What Happens to Gifts or Inheritances I Received?
It’s a common assumption that a gift or inheritance is automatically yours to keep, no questions asked. While that’s the general idea, the reality can be much more complicated. Under the Family Law Act, gifts and inheritances you received during the marriage can usually be excluded from your Net Family Property calculation, meaning they aren’t split.
But there’s a massive catch: you lose this protection if you mix, or “commingle,” those funds with family assets. For instance, if you inherit $50,000 and put it into a joint bank account or use it to pay down the mortgage on the matrimonial home, that money is very likely to be treated as a family asset and get divided.
Want to protect an inheritance or gift? The trick is to keep it completely separate. Open a new bank account in your name only and never let those funds touch your joint finances. Meticulous records are your best friend if you ever have to prove the money was always separate.
How Are Our Debts Divided in the Divorce?
Debts are just as important as assets when figuring out the financial picture. Mortgages, car loans, lines of credit, and credit card balances—any debt built up during the marriage is considered a family liability. It all gets factored into the equalization process.
When we calculate your Net Family Property, the value of your debts on the date of separation is subtracted from the value of your assets. This means if your name is on a joint credit card, you are legally on the hook for the entire balance, even if your spouse did all the spending. It’s crucial to deal with joint debts head-on in a Separation Agreement, spelling out exactly who is responsible for paying off each one.
What if We Were Common-Law?
This is a huge point of confusion for couples in Brampton, and the rules are completely different. In Ontario, common-law partners do not have the same property rights as married spouses. There is no automatic right to equalization, which means there’s no automatic 50/50 split of the property you acquired together.
When a common-law relationship ends, you generally leave with the assets and debts that are in your name. The special protections for a “matrimonial home” don’t apply, so if the house is solely in your partner’s name, you have no automatic right to stay there.
That said, you may have options. If you made significant contributions to an asset your partner owns—like paying for major renovations on their house—you might be able to make a trust claim to be compensated. These claims are complex and hinge on providing detailed proof of your contributions, making expert legal advice absolutely essential.
Navigating property division requires a clear head, a solid strategy, and professional guidance. The team at Badesha Law is here to protect your rights and help secure your financial future in Brampton. Whether you need to draft a fair Separation Agreement or are facing a contentious dispute, we provide the strong, client-focused advocacy you deserve. Contact us to ensure your interests are protected every step of the way.