

If you're heading into a separation or divorce in Ontario, you're going to get very familiar with Form 13.1: Financial Statement. This isn't just another piece of paperwork; it's the single most critical document that will shape the entire financial outcome of your case, from child support and spousal support to the division of your property.
Think of it as the mandatory, sworn foundation upon which all financial negotiations are built.
Why Form 13.1 Is The Cornerstone Of Your Family Law Case
When a relationship ends, the task of untangling years of shared finances can feel completely overwhelming. The law demands a structured, transparent process to make sure things are handled fairly, and Form 13.1 is the tool that makes it happen. It’s the official map of your financial life that both you, your ex-partner, and the court will use to navigate every decision about money.
The entire point is to force complete financial transparency. In Ontario family law, this document is required for any case involving property division or support claims. It's not optional. Under Family Law Rule 13(1), you are legally required to serve and file it with any application that touches on financial matters. This rule protects everyone by ensuring all cards are on the table from the very beginning.
The Three Critical Valuation Dates
What makes Form 13.1 so powerful is its focus on three specific points in time. You’ll have to calculate the value of all your assets and debts on these exact dates:
- Date of Marriage: This sets the financial baseline for when your partnership began.
- Date of Separation: This marks the official end of your financial partnership.
- Current Date: This provides a real-time view of where things stand today.
These three snapshots aren't random. They are used to perform the crucial calculation required by Ontario's Family Law Act to determine your Net Family Property (NFP). The court then compares your NFP to your spouse's NFP, and the difference usually results in an equalization payment—a lump sum paid from one spouse to the other to ensure the property built during the marriage is shared equally.
The accuracy of your Form 13.1 is everything. A judge will rely on this sworn document to make decisions that will affect your financial life for years. Any omissions, mistakes, or outright lies can destroy your credibility and lead to severe legal and financial penalties.
More Than Just a Form
For many people, filling out this document is the first time they've ever had to take such a deep, detailed inventory of their finances. It’s a demanding process. You have to track down bank statements, get property and pensions appraised, and account for absolutely everything you own and owe.
To make sense of what you're compiling, it can be really helpful to understand the basics of how to read financial statements for beginners. This little bit of background knowledge can make the whole task feel a lot less intimidating.
Getting this form right from the very start is absolutely crucial. It sets the tone for negotiations, mediation, and any court hearings that might follow. A complete and accurate statement can streamline the entire process, reduce conflict, and end up saving you a significant amount of time and legal fees. For a deeper dive into the legal framework, take a look at our guide on family law rights and responsibilities in Canada.
Accurately Disclosing Your Income
Part 1 of your Form 13.1 financial statement is all about income, but it goes way beyond the number on your bi-weekly paycheque. Think of this section as the engine that drives all support calculations. Its accuracy isn't just important—it's paramount. Every single dollar you earn, from every possible source, has to be declared transparently and backed up with hard proof.
The court needs a complete and honest picture of your financial capacity. This isn’t just about your base salary; it’s about bonuses, commissions, overtime, self-employment earnings, investment income, and even government benefits. Failing to disclose even a minor income stream can shatter your credibility and lead to serious legal consequences down the road.
More Than Just Your Salary
Your total income is a puzzle, and your T4 salary is just the biggest piece. To give the court the full picture, you have to account for all the other streams of revenue that complete it.
For many professionals in the GTA, income isn't a fixed, predictable amount. A sales professional in Brampton might have a modest base salary but earn significant commissions, while a freelance graphic designer in Mississauga might have wildly fluctuating project income month to month. Both of these scenarios demand careful calculation and full, honest disclosure.
Here are the common income sources you absolutely must include:
- Employment Income: This covers your salary, wages, bonuses, and any overtime pay.
- Self-Employment Income: You need to report your gross business income and then deduct legitimate business expenses. Be ready to justify every single deduction.
- Investment Income: This includes dividends from stocks, interest earned from savings accounts or GICs, and any capital gains.
- Rental Income: If you own a rental property, you must declare the gross rent you receive.
- Benefits and Pensions: This means income from CPP, private pensions, EI, or any disability benefits.
Calculating Variable Income
Figuring out income that isn't a fixed salary can be tricky. While the Family Law Act and the Child Support Guidelines provide the official framework, the general rule is to present an average that is fair and truly representative of your earnings.
If you have variable income, like a real estate agent, you can't just pick your best month or your worst. The court will typically look at a three-year average to establish a pattern and determine a fair income for support purposes. This approach smooths out any unusually high or low earning periods to land on a realistic number. To see how these numbers get plugged into the formulas, you can check out our overview of the spousal support calculator in Ontario.
Real-World Scenario: A construction contractor in the GTA earns the bulk of their income during the busy spring and summer months. On their Form 13.1, they can't just use their lower winter earnings. Instead, they must use their total annual income from the past three years to calculate a monthly average, which gives a far more accurate picture of their true earning capacity.
The Essential Paper Trail
Your income disclosure is only as strong as the documents that back it up. You can't just write down numbers and expect the court to take your word for it. You are required to attach specific documents to your Form 13.1 to verify every single figure you claim.
This isn't a suggestion; it's a mandatory requirement. Your filing will be considered incomplete—and likely rejected—without this essential backup.
Key Documents to Attach:
- Income Tax Returns: You must provide your complete personal income tax returns for the last three consecutive years.
- Notices of Assessment (NOA): Your NOAs from the Canada Revenue Agency for the last three years are also required, along with any Reassessment notices. These are crucial because they confirm the CRA's official assessment of your filed returns.
- Proof of Current Income: You’ll need to attach your most recent pay stubs or a formal statement from your employer that details your year-to-date earnings. If you're self-employed, a recent profit-and-loss statement is what you'll need.
Gathering these documents early is one of the most important things you can do to get started. Being organized and thorough here prevents frustrating delays and shows the court that you're participating in the process transparently and in good faith.
Calculating Your Net Family Property
After you’ve laid out your income, Form 13.1 gets to the real heavy lifting: calculating your Net Family Property (NFP). This is the heart of Ontario’s property division process, and getting it right is everything. Parts 2 through 6 of the form are designed to walk you through this calculation, turning a complex legal formula into a step-by-step financial inventory.
The whole point is to list and value every single asset and debt you have on three specific dates: the day you got married, the day you separated, and right now. This reveals the financial value each of you built up during the marriage, which is then divided equally.
Valuing Your Assets and Debts Across Time
Your first big task is to build a detailed inventory of your financial life. You need to list everything you own, from big-ticket items like your house and investments down to your car and any valuable collections. This isn't the time for guesswork; it’s a meticulous process that demands total transparency.
For each item, you’ll have to assign a fair market value for all three key dates. This can be a real headache, especially for assets that change in value.
- Real Estate: For your matrimonial home or any other properties, you'll almost certainly need a professional appraisal to get an accurate value for the separation and current dates.
- Vehicles: You can use resources like the Canadian Black Book or get a dealer appraisal to figure out what your car, boat, or motorcycle is worth.
- Bank Accounts & Investments: This means digging up old statements from your bank or brokerage to find the exact balances on your marriage and separation dates. Start this process early—it can take a while.
- Pensions: Valuing a company pension is incredibly complex. It’s not something you can just estimate. You will need a specialized actuarial valuation to determine its worth on the date you separated.
This simple diagram shows how your financial details come together for the disclosure process.
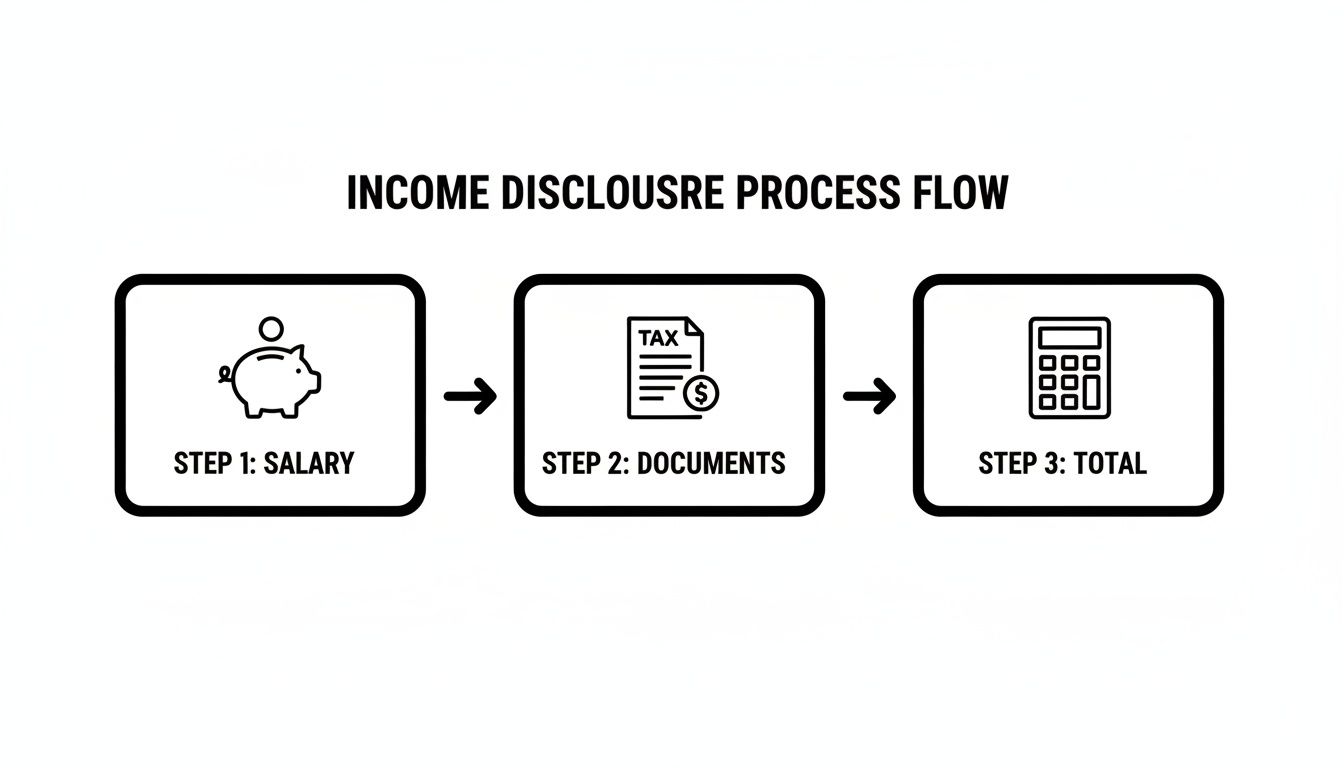
This flow—from income sources to supporting documents to a final total—is the same logic you'll use when listing and valuing every single asset and debt.
The Crucial Role of Excluded Property
One of the most important—and often misunderstood—parts of this section is excluded property. Ontario's Family Law Act recognizes that certain assets don't belong in the "family pot" to be divided. This means you can deduct their value from your total assets, which can have a massive impact on the final equalization payment.
Common examples of excluded property include:
- Gifts or inheritances received from a third party during the marriage.
- The value of property you already owned on your wedding day (except for the matrimonial home).
- Proceeds from a life insurance policy.
- Damages awarded to you from a personal injury lawsuit.
But there's a huge catch: you must be able to trace the excluded funds. If you got a $50,000 inheritance and dropped it into a joint bank account where it got mixed with family money and used for groceries and bills, it can lose its protected status. Keeping those funds separate is the key to protecting them.
A Brampton Couple Scenario
Let’s think about a local couple, Priya and Raj, who are separating in Brampton. Five years ago, Priya received a $100,000 inheritance from her aunt, which she wisely kept in a separate investment account in her name only.
When filling out her Form 13.1, Priya would list the current value of that investment account under her assets. But she would also claim a $100,000 deduction as excluded property. This ensures her inheritance isn't unfairly split with Raj. If she had used that money for a down payment on their shared matrimonial home, the situation would be far more complicated.
Demystifying the Equalization Calculation
Once all your assets, debts, and exclusions are listed, the form guides you through the final calculation. Here’s a simplified version of how it works:
- Calculate Assets on Separation Date: Add up the value of everything you owned the day you separated.
- Subtract Debts on Separation Date: From that total, subtract all your liabilities as of that date.
- Subtract Excluded Property: Next, deduct the value of any property you’ve properly claimed as excluded.
- Subtract Net Worth on Marriage Date: Finally, subtract what you were worth (assets minus debts) on the day you got married.
The number you're left with is your Net Family Property. Your spouse will do the exact same calculation. The person with the higher NFP then pays half of the difference to the person with the lower NFP. This is called an equalization payment. The accurate calculation of your Net Family Property is a critical step when drafting a Divorce Settlement Agreement.
Getting these sections right is absolutely essential for a fair outcome. It’s where the financial results of your separation are truly decided.
Detailing Your Budget and Special Expenses
Once you've mapped out your assets and debts, Form 13.1 shifts its focus from your financial past to your day-to-day reality. Part 7, your proposed monthly budget, is far more than just a list of expenses—it tells a story about your financial needs and standard of living. This section is absolutely critical if you're making or responding to a claim for spousal support, or if you need to argue that a support amount would cause you undue hardship.
The court looks at your budget to understand what it actually costs for you to live each month. Let's be blunt: inflating your numbers or guessing will destroy your credibility. The key is to be meticulous and ground every single figure in actual, provable spending.
Building a Justifiable Monthly Budget
Your best friends in this process are your bank and credit card statements from the last six to twelve months. This historical data is what moves you from guesswork to fact-based reporting. You need to go through those statements line by line, categorizing every single expense.
Common budget categories you’ll need to account for include:
- Housing: Mortgage or rent, property taxes, condo fees, utilities, and home insurance.
- Transportation: Car payments, insurance, gas, maintenance, and public transit passes.
- Personal Care: Haircuts, toiletries, and other personal grooming expenses.
- Food and Household Supplies: Groceries, cleaning supplies, and other day-to-day necessities.
- Health: Prescription drugs, dental costs not covered by insurance, and other medical expenses.
A well-prepared budget is your evidence. If you claim you spend $800 per month on groceries, your bank statements better back that up. Judges have seen thousands of these forms and can spot an exaggerated or unrealistic budget in a heartbeat.
Accuracy is your greatest asset here. A detailed, verifiable budget strengthens your position, whether you're seeking support to meet your needs or demonstrating your actual financial capacity. This groundwork is also a key step when preparing a separation agreement and what you need to know.
Understanding Section 7 Special Expenses
Part 8 of Form 13.1 deals with a very specific category of costs known as special or extraordinary expenses. These are costs for your children that go above and beyond the basic monthly child support amount. Under Section 7 of the Child Support Guidelines, these expenses are shared between the parents in proportion to their respective incomes.
But not every extra cost makes the cut. For an expense to qualify under Section 7, it has to be both necessary for the child’s best interests and reasonable, considering the family's financial situation.
Examples of Qualifying Special Expenses:
- Health-Related: Orthodontics (braces), prescription glasses, counselling, or physiotherapy that isn't fully covered by insurance.
- Childcare: Costs you have to pay so you can work, go to school, or manage an illness.
- Education: Post-secondary education costs or private school tuition, but usually only if it matches the family's lifestyle before the separation.
- Extracurricular Activities: This typically means costs for high-level competitive sports (like elite hockey in the GTA) or specialized arts programs, not just house league soccer.
Calculating Proportional Shares
Once an expense is agreed upon as "special and extraordinary," the cost is split based on each parent's Line 15000 income from their tax returns.
Let’s run through a quick scenario:
- Parent A’s income: $100,000
- Parent B’s income: $50,000
- Total combined family income: $150,000
- The annual cost for their child's competitive hockey is $6,000.
To calculate the shares, we see that Parent A earns two-thirds of the total income ($100,000 / $150,000 = 66.7%). They would be on the hook for $4,000 of the hockey fees. Parent B, earning one-third, would cover the remaining $2,000. This formula ensures the financial weight is shared fairly, reflecting each parent's ability to contribute.
Common Mistakes We See and How to Avoid Them
A small error on your Form 13.1 financial statement can snowball into a major headache. From our experience in the Brampton and GTA courts, we've seen how simple mistakes lead to costly legal disputes, drawn-out delays, and a total loss of credibility in front of a judge.
Honesty and thoroughness aren't just suggestions; they are your best strategy for getting through this process smoothly. Think of this section as a final gut check before you sign and swear to the accuracy of your financial life. Getting these details right from the start protects you from a world of unnecessary complications down the road.
Undervaluing or "Forgetting" Assets
One of the most frequent and damaging errors we see is the undervaluing of assets. It’s tempting to assign a lowball value to your truck, your collectible art, or that expensive set of tools in the garage, but this is a serious misstep.
Equally problematic is "forgetting" to disclose a small TFSA, a line of credit with a zero balance, or an old cryptocurrency account you haven't touched in a while. The other side’s lawyer will scrutinize your statement, and if they find an asset you’ve undervalued or failed to disclose, it immediately raises red flags.
The Real-World Consequence: If you aren't transparent, a judge can draw an "adverse inference" against you. This means they can assume you're hiding other things, which completely tanks your credibility. They can also impute a value to the asset—often a higher one than its actual worth—or order you to pay the other side's legal costs for the time they spent uncovering your mistake.
Incomplete Documentation
Submitting your Form 13.1 without every single required supporting document is like turning in an exam half-finished. You simply cannot file the form without attaching your complete tax returns and Notices of Assessment for the last three years, plus proof of your current income.
This isn't a minor administrative slip-up. The court clerk will almost certainly reject an incomplete filing, causing significant delays and potentially making you miss critical deadlines.
To help you get organized, here’s a quick reference for the essential documents you'll need to gather before you even think about filing.
Form 13.1 Document Checklist
| Document Type | Why It's Needed | Where to Find It |
|---|---|---|
| Tax Returns (3 years) | Verifies your historical income and financial claims, showing a pattern of earnings. | Your accountant or your CRA My Account portal. |
| Notices of Assessment | Confirms the CRA's official assessment of your tax returns for those three years. | Your personal files or downloadable from your CRA My Account. |
| Recent Pay Stubs | Shows your current, year-to-date earnings and any deductions. | Your employer's payroll department or online employee portal. |
| Bank/Investment Statements | Proves the value of all financial assets on key dates, like the date of separation. | Your financial institution's online portal or by requesting archived statements. |
Having this package complete and ready to go is non-negotiable for a successful filing.
Miscalculating Income and Expenses
Guessing your monthly budget figures is another common pitfall we see all the time. Stating you spend $1,000 on groceries when your bank statements clearly show an average of $600 is an inconsistency that is easily disproven.
The same goes for income—if you’re self-employed, you can’t just estimate your earnings or use a ballpark figure. The court expects you to use actual data from bank statements, credit card bills, and business records to build your budget.
For income, especially if it fluctuates, a three-year average is the standard practice. An inaccurate income figure directly leads to incorrect support calculations, which will be challenged and ultimately corrected by the court, costing you a great deal of time and money.
When You Need Professional Legal Guidance
Let’s be honest, you can fill out a Form 13.1 financial statement on your own. But there’s a critical point where the process shifts from tedious paperwork to a high-stakes financial exercise—a point where trying to DIY can be a costly mistake.
If your financial picture is anything more than a straightforward salary and a few basic assets, the risk of getting it wrong skyrockets. Navigating the murky waters of a family business valuation, properly accounting for stock options, or trying to trace hidden assets requires a deep understanding of both finance and family law.
An experienced lawyer does more than just fill in the blanks. They ensure your financial disclosure is not only accurate but strategically prepared to support your overall goals in the case.
When Legal Counsel Is Non-Negotiable
Some financial scenarios are so complex that they almost always demand professional guidance to protect your interests. It’s in these situations that a small mistake can have massive consequences.
- Complex Income: If you or your spouse are self-employed, own a corporation, or earn a variable income from commissions, figuring out the correct number for support calculations is notoriously tricky.
- Hidden or Undisclosed Assets: Do you have a gut feeling your spouse isn’t being completely honest about their finances? A lawyer can use formal legal tools to compel full disclosure and uncover what’s really there.
- Significant Excluded Property: If you’re trying to protect an inheritance or a large gift from being divided, you have to trace it meticulously. This is a task loaded with legal pitfalls that are easy to fall into.
The whole point of this exercise is to secure a fair and legally sound outcome. An error in valuing a business or a pension can lead to a lopsided equalization payment, potentially costing you tens or even hundreds of thousands of dollars in the long run.
At Badesha Law, our day-in, day-out familiarity with the Peel Region courts gives us a unique insight into how judges here interpret financial information. Understanding the benefits of hiring a local Brampton family lawyer can be the single factor that separates a manageable process from a costly, drawn-out dispute. We can help you see clearly when a DIY approach is good enough—and when you need an expert to secure your financial future.
Brampton Clients Often Ask…
Navigating the Form 13.1 financial statement is a detailed process, and it almost always brings up practical, real-world questions. Here are some clear, straightforward answers to the concerns we hear most often from our clients here in Brampton and across the GTA.
What Happens If My Spouse Refuses to Provide Their Financial Disclosure?
This is a scenario we see all too often, but the law is crystal clear: financial disclosure is not optional. If a spouse fails to provide their Form 13.1, the court can—and will—impose serious penalties under the Family Law Rules.
A judge has the power to:
- Order them to pay your legal costs for causing the delay.
- “Strike” their court documents, which means their own claims might not even be heard.
- Make a final order based only on the financial information you have provided, which is a massive risk for the non-disclosing party.
How Often Do I Need to Update My Form 13.1?
Think of your financial statement as a current snapshot of your financial reality. It has to be up-to-date. You are legally required to update your Form 13.1 if your finances change in any significant way during your case—for example, if you get a new job, lose a job, or receive a large inheritance.
It must also be updated and re-sworn before any major court appearance, like a case conference or a motion. This ensures the court is always working with the most current information when making decisions that will absolutely impact your future.
What If I Don’t Know the Exact Value of an Asset from the Date of Marriage?
This is an incredibly common problem, especially for couples who were married for many years. Don’t panic. You are expected to make a reasonable and honest effort to find the value. This might mean digging through old filing cabinets for bank statements or contacting a financial institution to see if they can pull archival records.
If you’ve exhausted all options and simply cannot find the exact value, the next step is to provide a well-reasoned estimate. The key is to be prepared to explain exactly how you arrived at that figure.
Can I Fill Out Form 13.1 Myself Without a Lawyer?
Yes, you are legally permitted to complete and file the form on your own. However, given its central importance and complexity, this is one of those areas where trying to save a little money can cost you dearly in the long run.
Having an experienced family lawyer review it is crucial to avoid costly errors or omissions. For any situation involving a business, complex investments, pensions, or arguments over excluded property, getting professional legal advice isn’t just recommended—it’s essential for protecting your financial interests.
Navigating the complexities of a Form 13.1 Financial Statement can be a challenge, but you don’t have to do it alone. The experienced team at Badesha Law provides clear, step-by-step guidance to ensure your financial disclosure is accurate, complete, and strategically prepared to protect your future. Contact us for a consultation to move forward with confidence.